Builders Risk · Utah · Idaho · Arizona · Colorado
Builders Risk Insurance for Projects Under Construction
Builders Risk coverage protects your building or dwelling while it's being built, when the risk of fire and related perils is at its highest. For your project, you need adequate limits, the right endorsements, and an agency that understands Builders Risk insurance.
- Replacement Cost
- No Coinsurance
- $100K in Transit
- $100K in Off-Site Storage
- Up to 5% Automatic Limit Escalation
What It Covers
Builders Risk Insurance
Builders Risk insurance covers the building or dwelling during the construction process. Projects under construction are at a higher risk of fire and related perils, and that is not a time to take chances with your coverage. Make sure you have adequate limits and work with an agency that understands Builders Risk.
Anderson Insurance Group is a family owned, independent insurance agency representing the best companies in Utah for your Builders Risk coverage. Not all Builders Risk policies are the same: some coverages are essential, and there are optional coverages that should be in every policy so you are not caught off guard in the event of a loss.
Your Project
Insured From the Ground Up
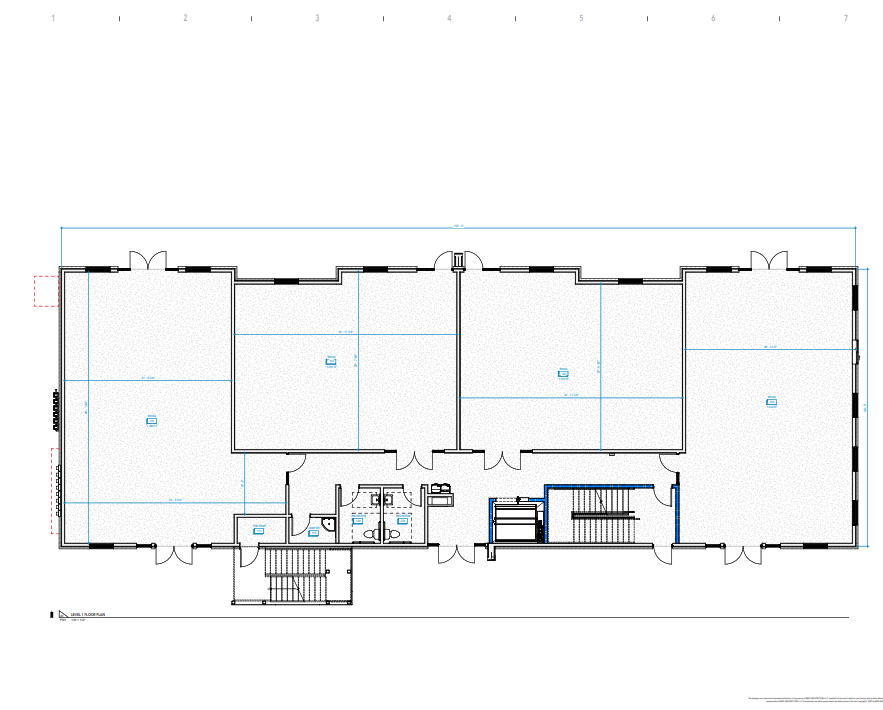
From the site plan to the finished structure, your Builders Risk policy follows the build. Take a closer look at the plan.
Hover to zoom in
Project Gallery
From Rendering to Reality
Builders Risk follows your project through every stage of construction. This is what that looks like on site.
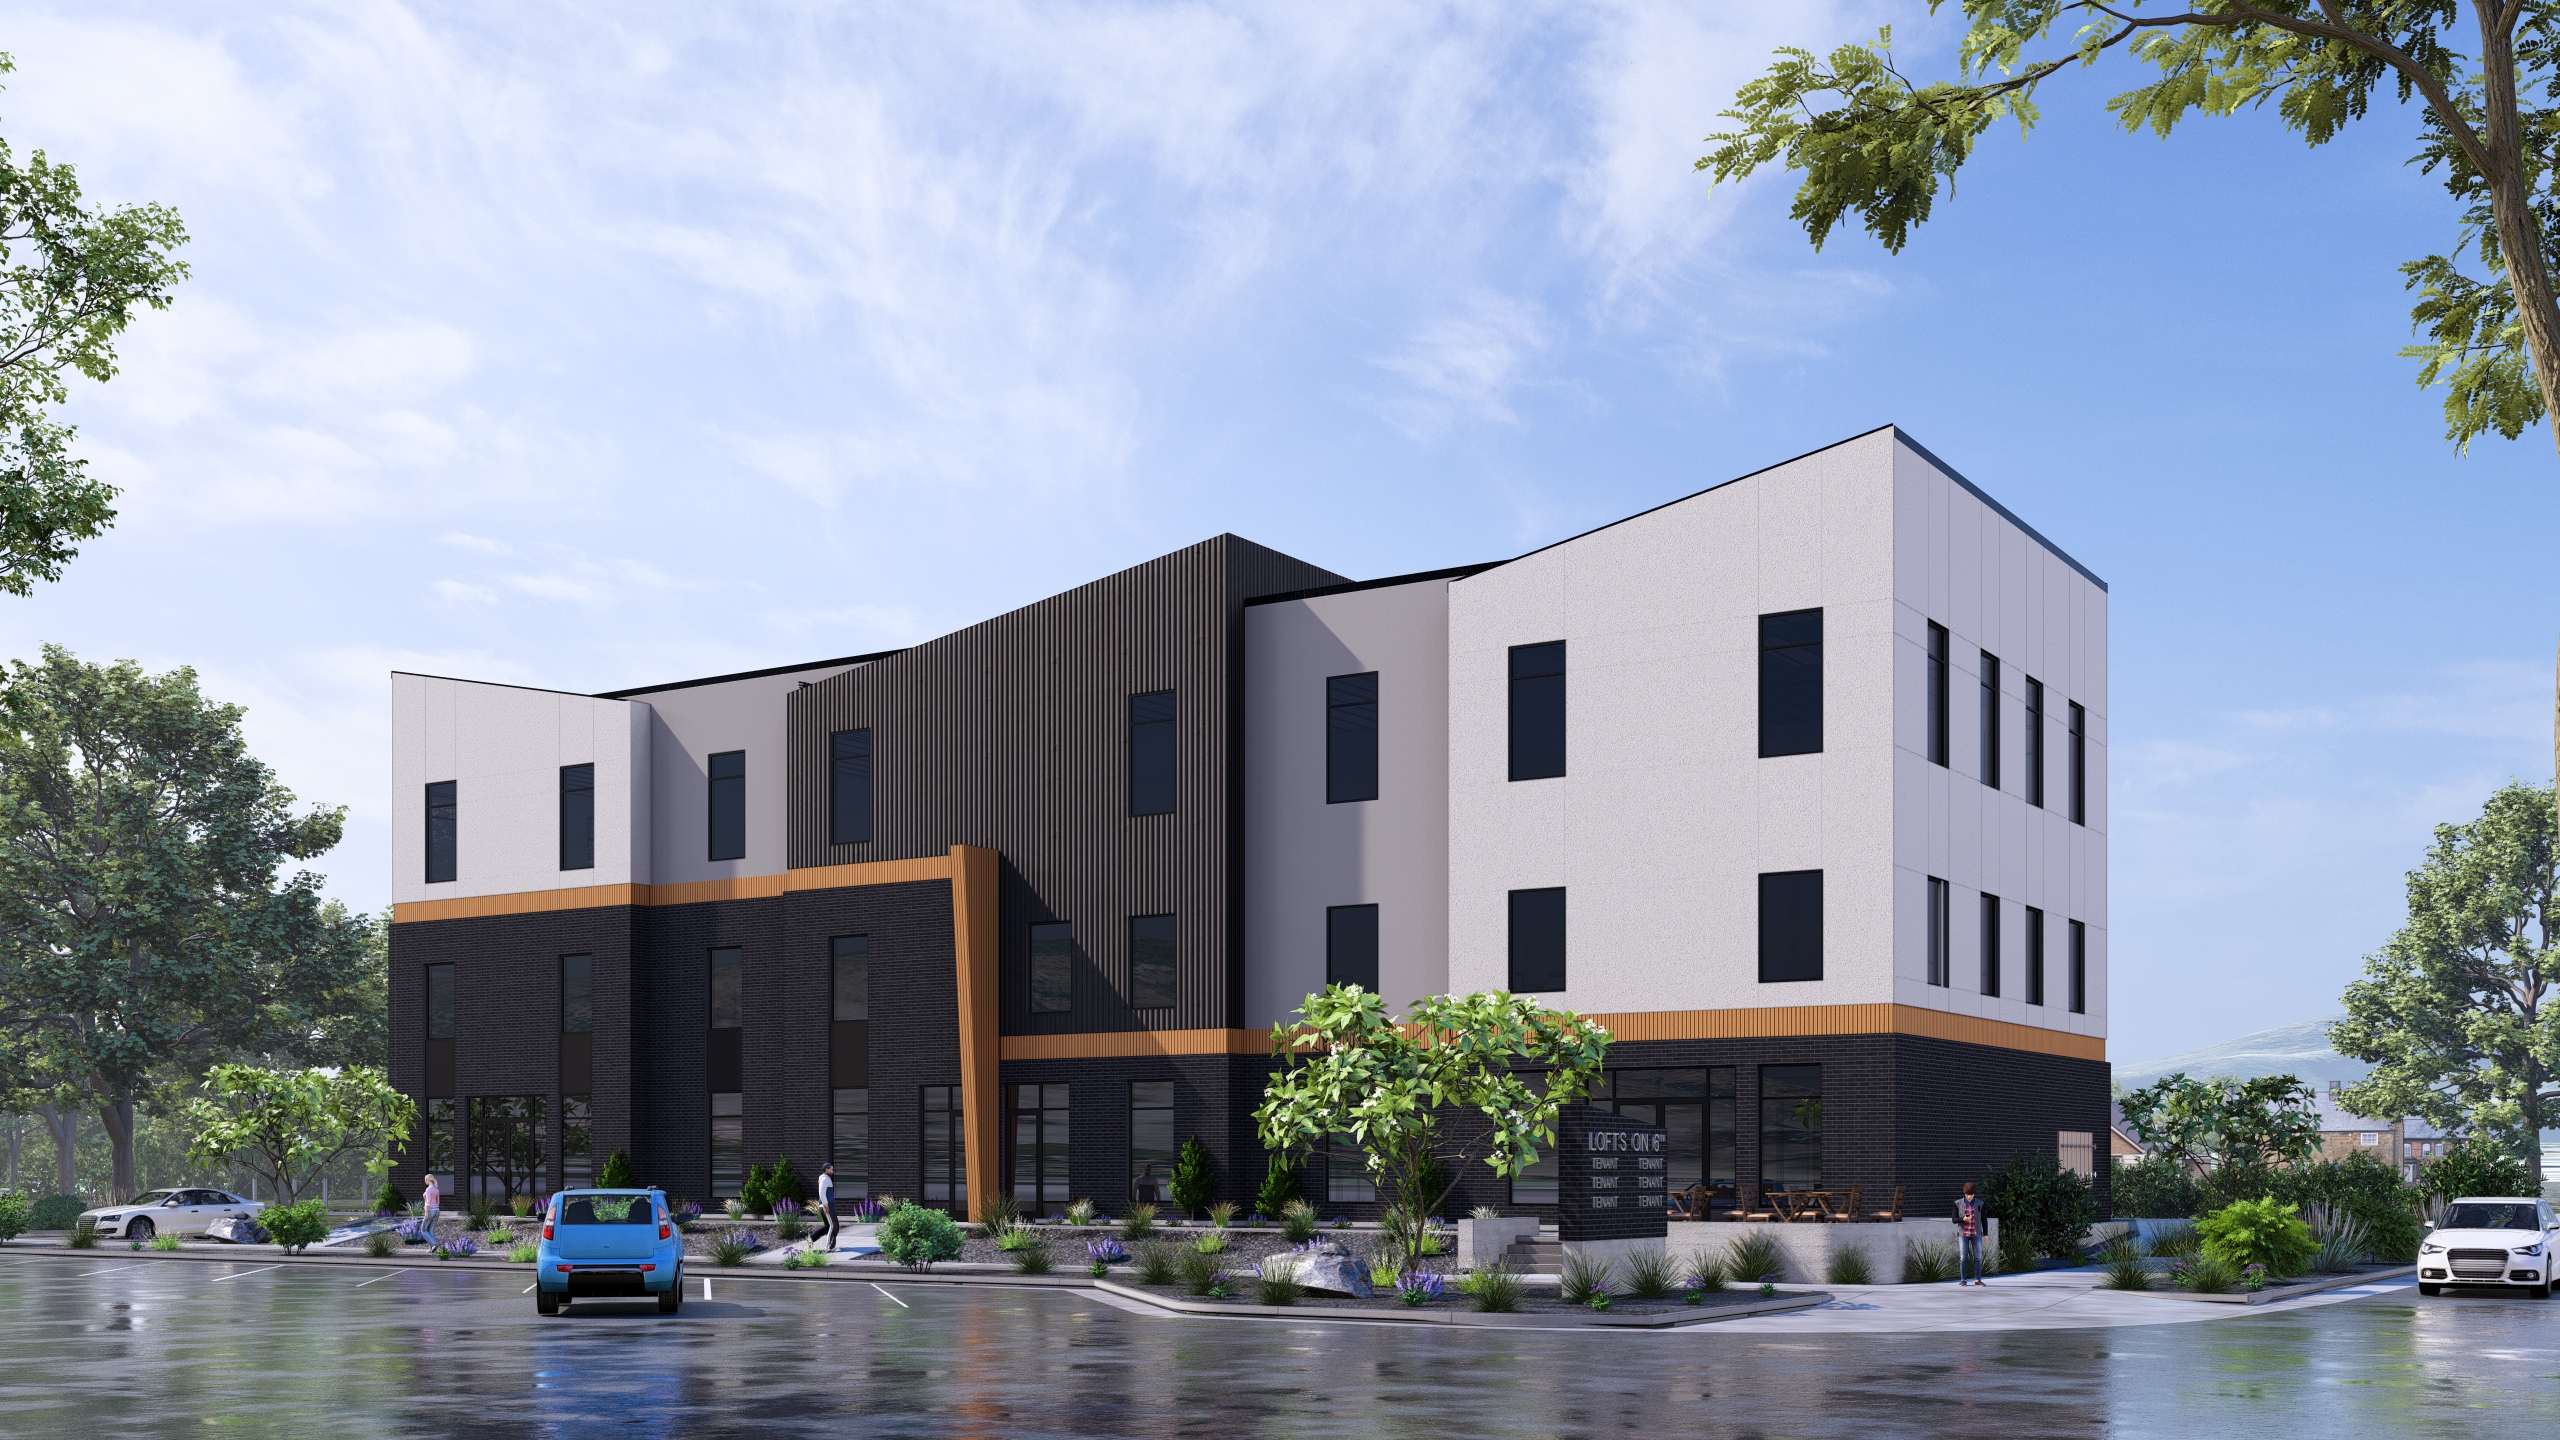
The rendering
The finished vision, before ground is broken.
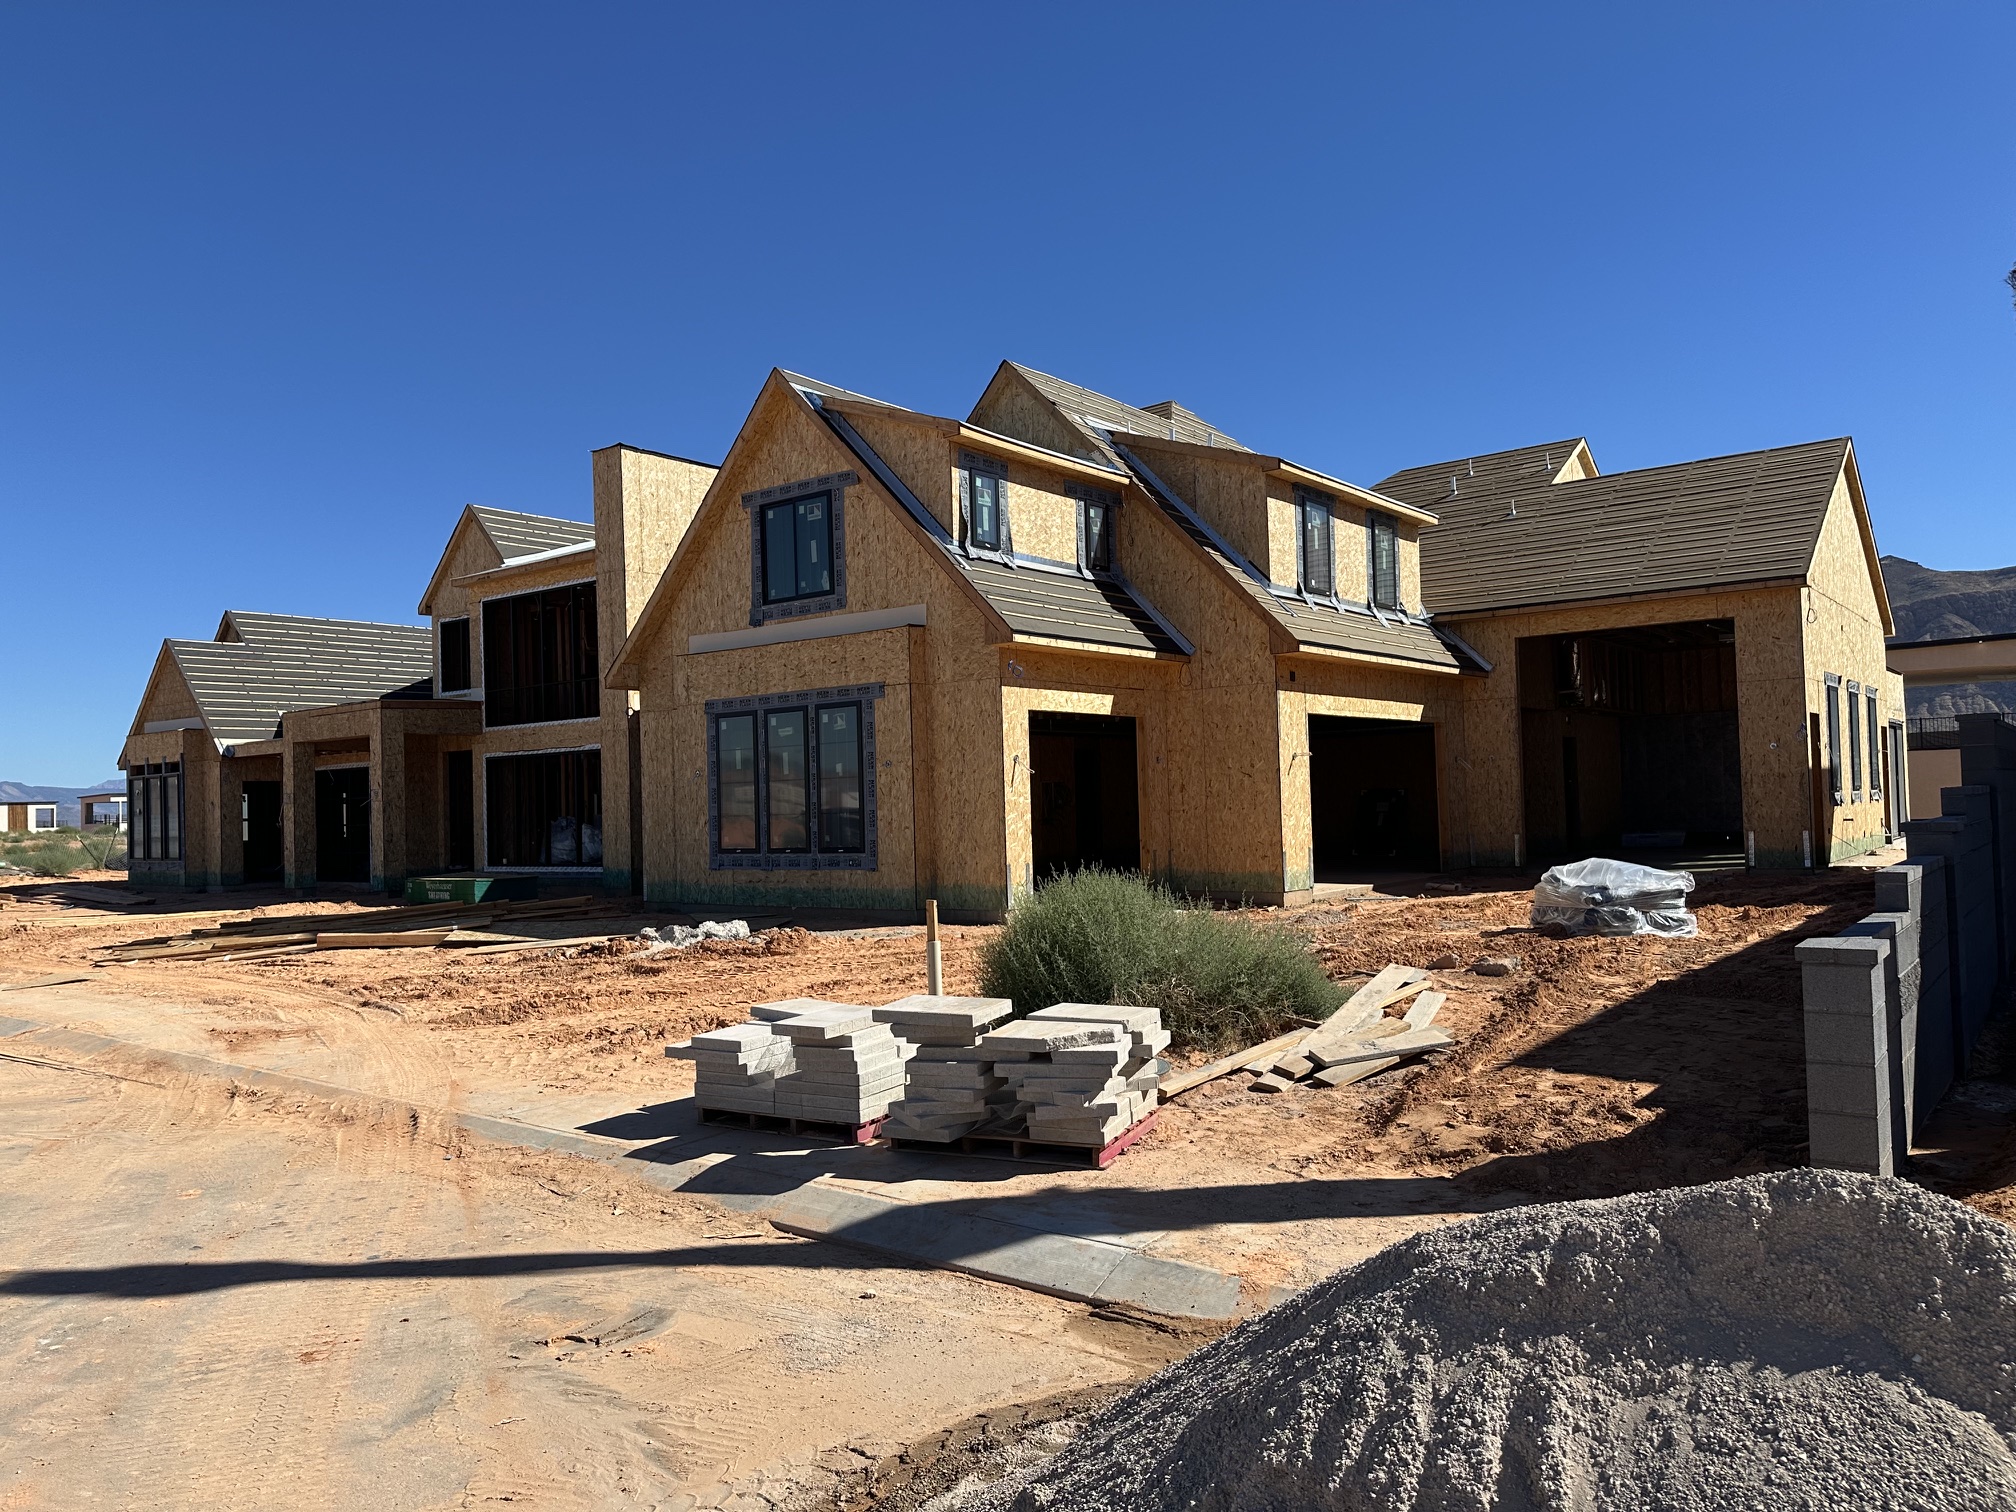
Framing & sheathing
Walls up and roof on, when fire and theft risk climb.
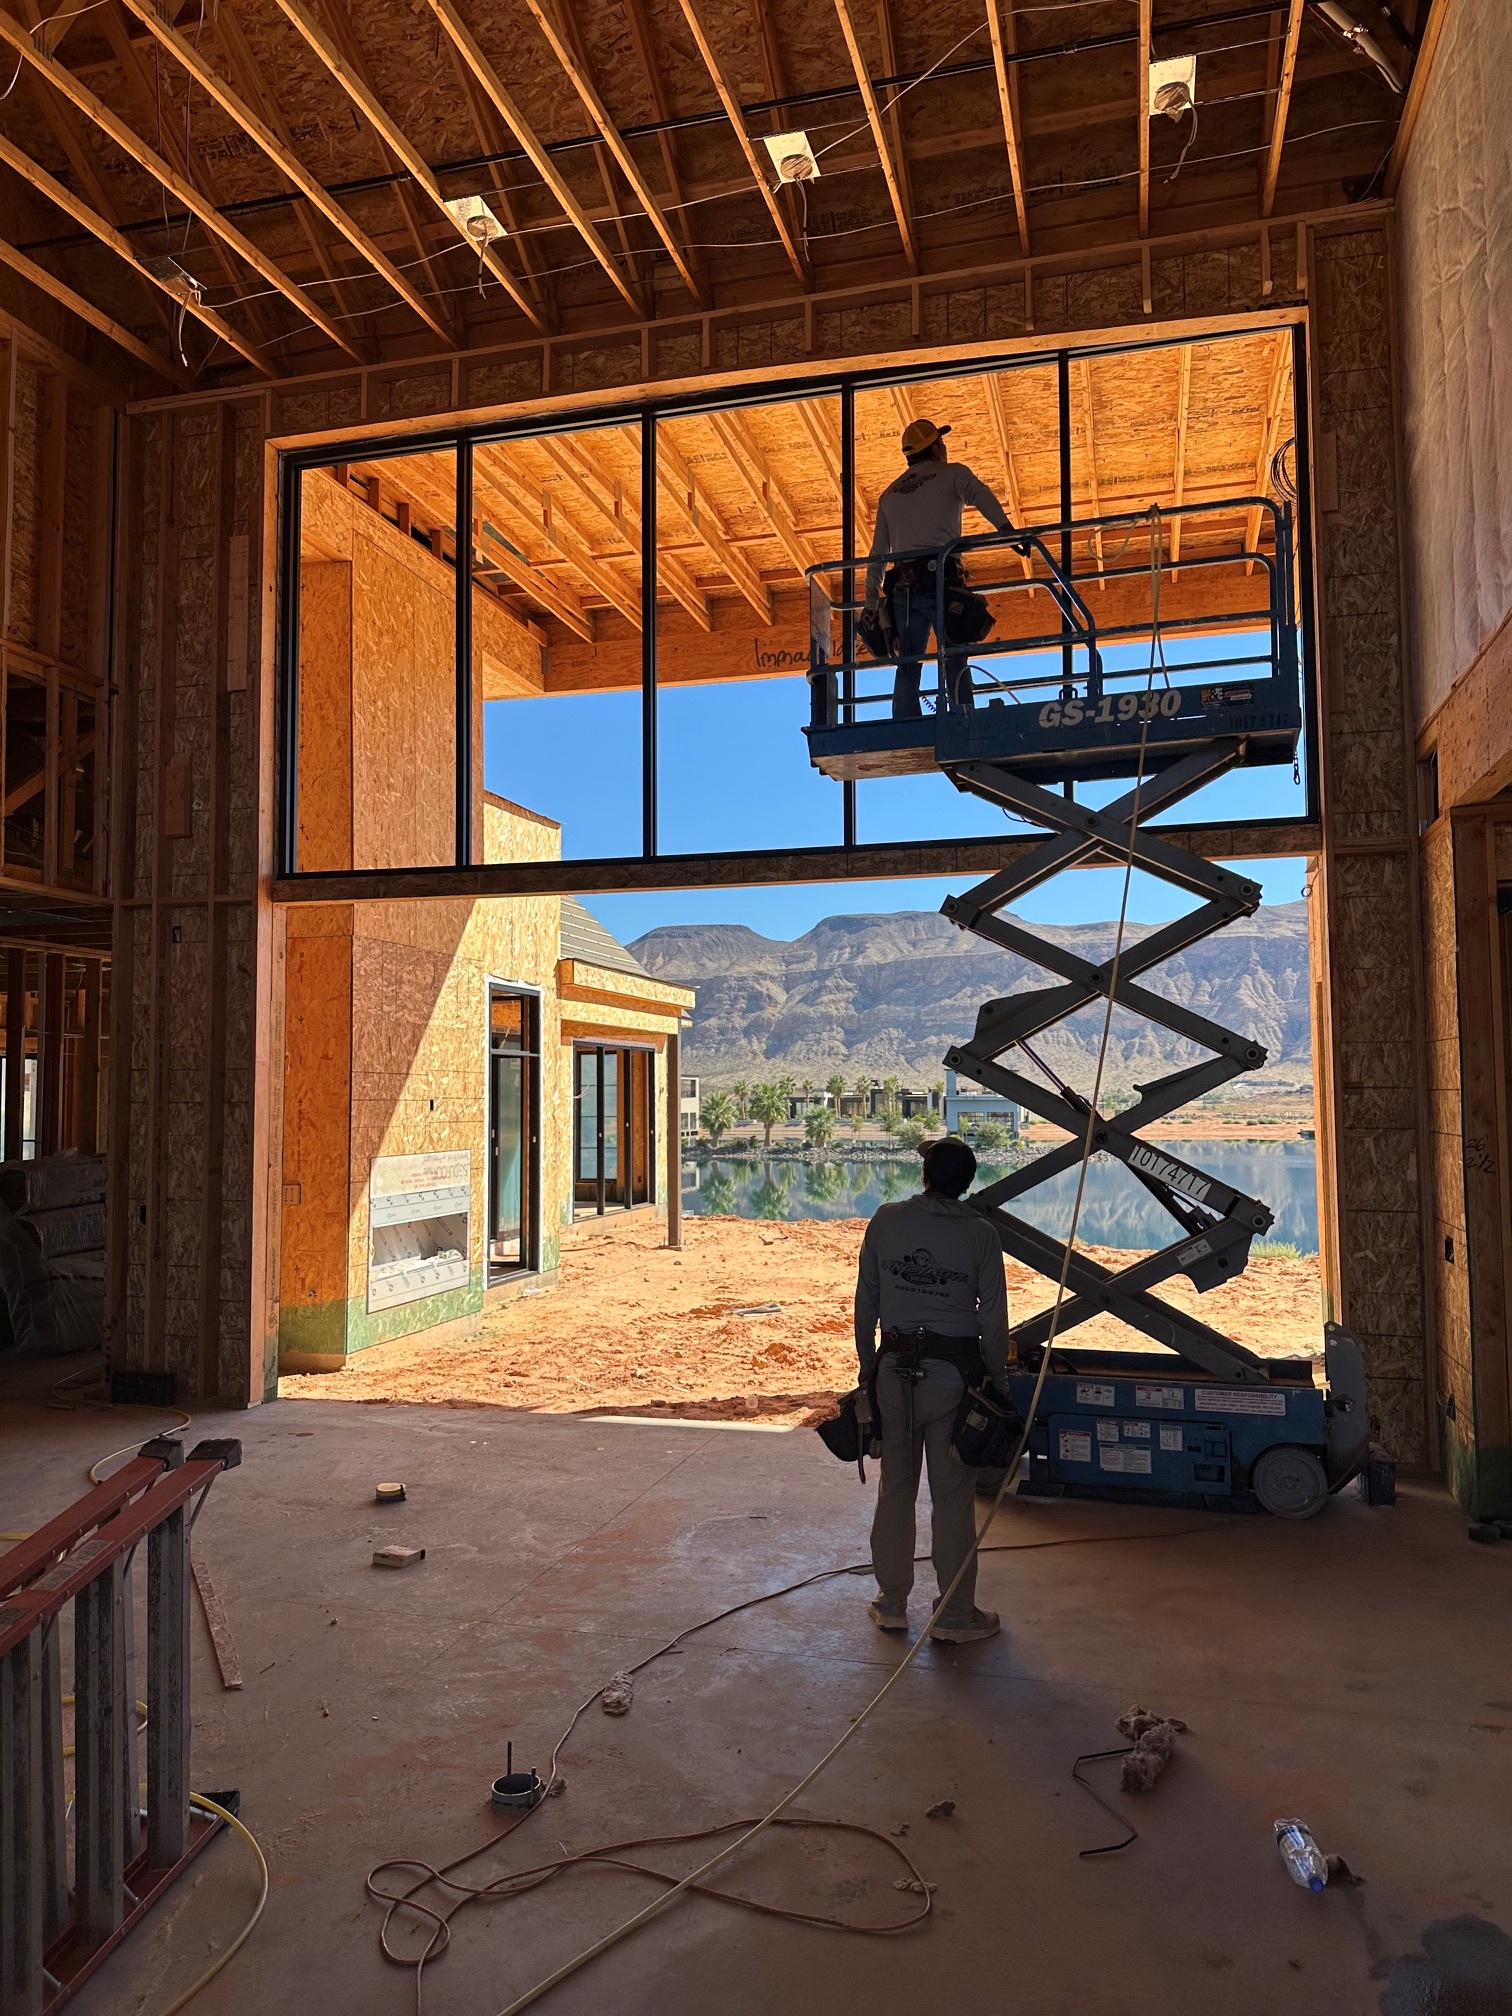
Windows & interior
Crews and equipment on site every day.
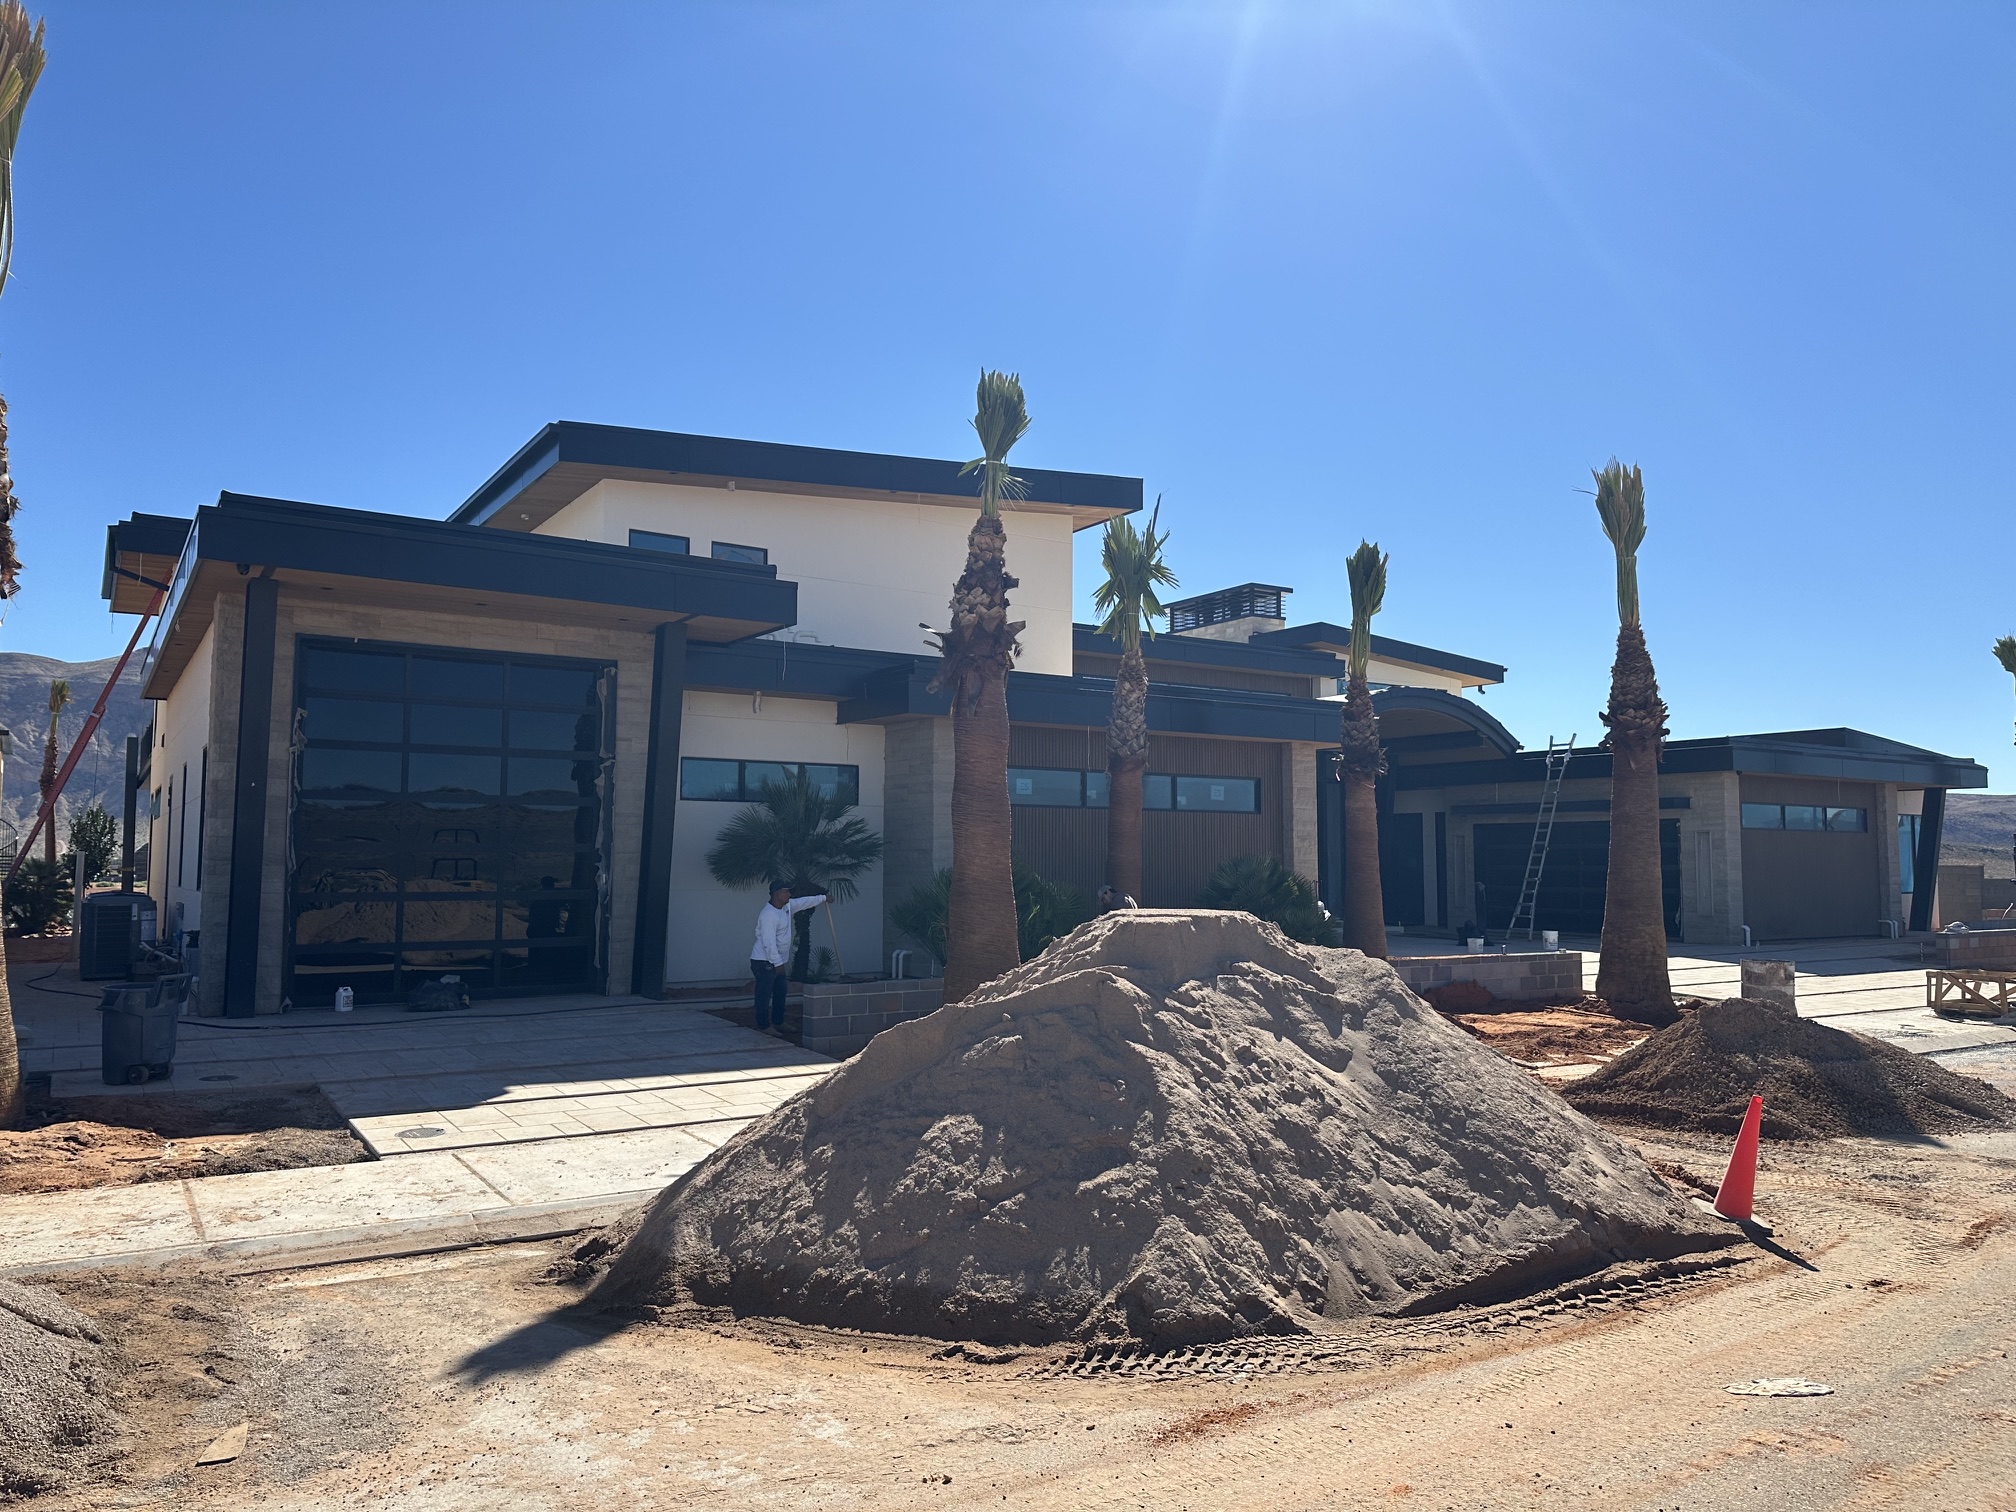
Finishing & landscaping
The last stretch, and the time to line up permanent coverage.
Robust Core Property Coverage
The Coverage at the Heart of the Policy
The primary protection for your project, from the foundation up and everything that supports the build.
High Project Limits
The structure
Primary coverage for the building or structure during construction, erection, or fabrication.
Included Construction Assets
Beyond the walls
Extends beyond the foundation and walls to scaffolding, construction forms, cribbing, falsework, shoring, temporary structures, and office trailers servicing the project.
Off-Site & Supply Chain
In transit
Automatically includes $100,000 for covered property in transit and $100,000 for materials stored at unscheduled storage locations.
No Coinsurance Penalty
No surprises
The coinsurance clause does not apply, which prevents underinsurance percentage penalties at the time of a partial loss.
Replacement Cost Valuation
Full value
Covers losses at replacement cost without a depreciation deduction, including reasonable contractor overhead and profit as specified in the construction contract.
High-Value Extended Endorsements
The Builders' Risk Inland Marine Extended Coverage (MA 257)
Most of our policies include dedicated limits above and beyond the primary building limit. This is where the right Builders Risk policy earns its keep.
Up to 5%
Escalation of Limit
Automatically increases the primary limit by up to 5% in a total loss, to absorb rising labor and material costs or agreed change orders during the policy term.
$50,000
Soft Costs
Indirect losses from a covered construction delay: extra loan interest, extra real estate taxes, extended insurance premiums, and architectural, engineering or legal fees.
$100K + $100K
Ordinance or Law
$100,000 for demolition and site clearance (Coverage B) and $100,000 for increased cost of construction to meet newer codes (Coverage C). Undamaged portions (Coverage A) sit within the building limit.
$25,000
Contract Penalty Protection
Reimburses contractual delay penalties owed to clients if a covered physical loss causes the project to miss scheduled contractual delivery dates.
$50,000
Expediting Expenses
Pays for overtime wages, express freight, and rapid equipment rental needed to accelerate temporary or permanent repairs after a loss.
$75,000
Fraud & Deceit Protection
Covers theft when workers or agents are tricked into releasing building materials through fraudulent shipping receipts, fake delivery personnel, or cyber spoofing.
$50K + $50K
Debris Removal & Remediation
Adds $50,000 for debris removal beyond the standard 25% allowance, and $50,000 for pollutant cleanup and extraction from land or water.
$25,000
Claims Preparation Expense
Helps offset the professional expenses of preparing and documenting the details of a complex claim.
Pricing
What Does Builders Risk Cost in Utah?
Price depends on the value of the building, the class of construction, and the location. If the project qualifies for preferred rates, these are rough estimates by class of construction.
Frame
$0.25 – $0.30
per $100 of building limit
- Residential: $2,500,000 dwelling × .025 = $6,250 / year
- Commercial: $2,500,000 building × .025 = $6,250 / year
Joisted Masonry
$0.10 – $0.18
per $100 of building limit
- Commercial: $5,000,000 building × .15 = $7,500
- Brick or masonry outer walls with wood or metal frame floors, roof and inside walls.
Superior
$0.07 – $0.10
per $100 of building limit
- Commercial: $5,000,000 building × .085 = $4,250
- Non-combustible, fire-resistive and similar classes of construction.
Note: hardy board or fiber-cement siding, or a brick veneer outer layer, is generally classified as Frame. The standard Builders Risk deductible is $10,000 and increases for higher-value structures.
Before You Start
A Few Things to Plan For
Insure the finished project in time
Liability during construction is covered by the builder. As the project nears completion, make sure insurance is in place for the completed project before you finalize the agreement. Before construction starts, vacant-land liability can be handled a few ways. Best practice is to request a certificate of insurance from the builder showing the general liability limits that extend to your project, which is why insurers ask for the builder's name and website or proof they are licensed and credible.
Start the policy when construction begins
Builders Risk needs to start when construction begins. If you wait until after the project is already underway, coverage becomes difficult to find and very expensive.
Raise the limit if costs grow
As you approach completion, if the cost of construction has exceeded your building or dwelling limit, contact your insurance company to increase the limit.
Know your deductible
The standard deductible for a Builders Risk policy is $10,000, and it increases for higher-value structures.
Get Your Builders Risk Quote
Tell us about your project and a Builders Risk expert will build a customized quote for you.
FAQ
Builders Risk Insurance FAQs
What Utah owners and builders ask us most before a project starts.
When does Builders Risk coverage need to start?
When construction begins. If you wait until the project is already underway, coverage is much harder to find and far more expensive, so the best practice is to bind the policy as construction starts.
What is the standard deductible?
The standard Builders Risk deductible is $10,000, and it increases for higher-value structures.
Does it cover materials in transit or stored off-site?
Yes. The policy automatically includes $100,000 for covered property in transit and $100,000 for materials stored at unscheduled storage locations.
Does Builders Risk cover the finished building?
No. Builders Risk covers the building while it is under construction. Before the project is complete, arrange permanent property insurance so the finished building is covered the moment the Builders Risk policy ends.
What is the difference between Frame, Joisted Masonry and Superior construction?
Frame is wood or metal framing. Joisted Masonry has brick or masonry outer walls with wood or metal frame floors, roof and interior. Superior is non-combustible or fire-resistive. Lower fire risk means a lower rate, so Superior costs the least and Frame the most.
Get exact pricing for your project.
Reach out to an Anderson Insurance Group Builders Risk expert today for precise pricing and coverage details on your build.
Coverage descriptions are general and subject to the terms, conditions and exclusions of each policy. Rate estimates are illustrative and not a quote. Talk to a licensed agent about your specific project.